- New Braunfels Homes for Sale
- Home Buying
- Home Selling
- Rent
- New Braunfels Neighborhoods
- About
- Resources
- New Braunfels Real Estate Blog
- Register
- /
- Sign In
222 Properties Available In Canyon Lake
- Newest Listings
- Price-High To Low
- Default
- Price-Low To High
- Beds (Most)
- Baths (Most)
- Year Built (Newest)
- Square Feet (Biggest)

$257,900
1238 Qappuella, Canyon Lake, TX 78133
Manufactured Home
Listed by Lisa Polasek of RE/MAX Genesis • (210) 459-4259


$210,000
890 BLUE WATER DR, Canyon Lake, TX 78133
Vacant Land
Listed by Sherry Keeble of Exit 4 Texas • (830) 606-0606

$675,000
1382 Primrose PATH, Canyon Lake, TX 78133
Single Family Home
Listed by Alice LebkuecherofKeller Williams Realty - Partn


$2,100
651 HANCOCK RD, Canyon Lake, TX 78133-2628
Single Family Home, Other Rentals
Listed by Kimberly Gray of Keller Williams Heritage • (830) 837-4002
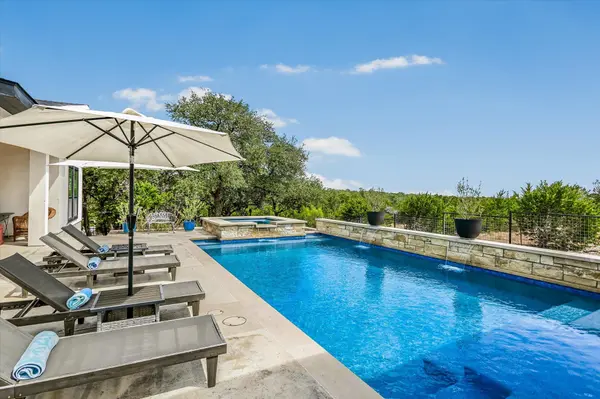
$675,000
1382 Primrose PATH, Canyon Lake, TX 78133
Single Family Home
Listed by Keller Williams Wimberley

$160,000
751 SCENIC TERRACE DR, Canyon Lake, TX 78133
Single Family Home
Listed by Joe Ramos of Reliance Residential Realty - • (830) 318-7765

$369,000
700 OAKLEAF DR, Canyon Lake, TX 78133
Single Family Home
Listed by Carlos Jaquez of Orchard Brokerage • (210) 860-2343

$550,000
2131 Fm 484, Canyon Lake, TX 78133
Single Family Home
Listed by Sullivan Hill Country Properti

$550,000
2131 Fm 484, Canyon Lake, TX 78133
Single Family Home
Listed by Crystal UnrueofSullivan Hill Country Properti

$550,000
2131 Fm 484, Canyon Lake, TX 78133
Single Family Home
Listed by Crystal Unrue of Sullivan Hill Country Properti • (830) 388-1887

$375,000
570 Forest Crest, Canyon Lake, TX 78133
Single Family Home
Listed by Risa SaldanaofSullivan Hill Country Properti

$189,999
611 Hedgestone, Canyon Lake, TX 78133
Manufactured Home
Listed by Elisa Wilcox of Keller Williams Heritage • (210) 288-0484
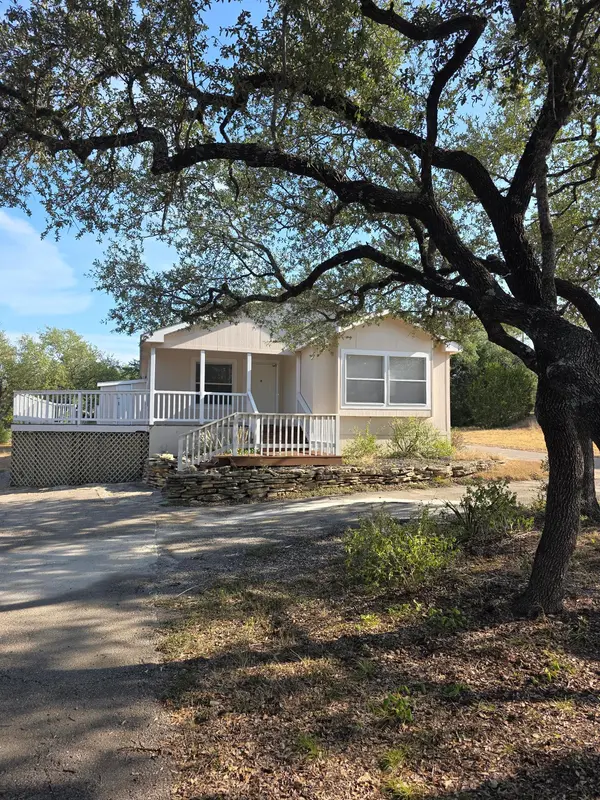
$1,675
1467 Live Oak DR, Canyon Lake, TX 78133
Manufactured Home
Listed by Tarpon Blue Real Estate

$295,316
2012 Ronda CT, Canyon Lake, TX 78133
Single Family Home
Listed by Fran DanielsofDaniels And Daniels Real Estat

$427,000
603 Barbara Dr, Canyon Lake, TX 78133
Single Family Home
Listed by Cindy Moore of Epique Realty LLC • (830) 237-0780

$2,000
1910 FM 2673, Canyon Lake, TX 78133
Single Family Home
Listed by Marc ColemanofCanyon Land Real Estate & PM

$235,000
1582 Valley DR, Canyon Lake, TX 78133
Single Family Home
Listed by Realty One Group Prosper

$319,000
464 Pecan Row, Canyon Lake, TX 78132
Single Family Home
Listed by Kimberly SpringfieldofKeller Williams Heritage

$649,000
1126 Ensenada Dr, Canyon Lake, TX 78133
Single Family Home
Listed by Dennis Heath of Option One Real Estate • (210) 564-7771

$1,650
1728 Colleen, Canyon Lake, TX 78133
Single Family Home
Listed by Kayla MyrickofPearl Realty
- 1
- 2
- 3
- 4
- 5
- ...
- 10
Home Buying Questions and Answers
Pre-Qualification: The "Pinky Swear"
This is a casual conversation. You tell a lender, "Hey, I make about this much and I owe about that much," and they say, "Cool, you can probably buy a $500,000 house."
Pre-Approval: The "Real Deal"
This is the heavy lifting. You give the lender the "receipts"—W-2s, pay stubs, bank statements, and they pull your actual credit score, and they Say you are pre-approved for $500,000.
The Real Cost of a "So-So" Score:
Lenders group people into "buckets" of 20 points. If you’re at a 739, you’re paying more than the guy at 740, even though there's only one point between you.
As of March 2026, here’s how the math is shaking out in Texas:
740+ Score (The Gold Standard): You’re seeing rates around 6.1% for a 30-year fixed.
620-640 Score (The "Just Barely"): You might be looking at 7.1% or higher.
On a $500,000 home, that 1% difference costs you roughly $300 a month. Over 30 years? That’s over $100,000 you just set on fire because your credit wasn't dialed in.
Your 3-Step Plan to a Better Rate:
Get the Truth: Don't trust those "free" apps that give you a fake score. You need a hard credit pull from a mortgage lender to see what the banks actually see.
Get the Keys: If your score is low, we don't give up. We look at FHA options (which allow scores as low as 580 with 3.5% down) or we work on "rapid rescoring" to bump you into the next bracket.
Get Home: Once that score is up, we lock in the lower rate, keep your monthly payment manageable, and get you into that New Braunfels backyard without the financial hangover.
Buying a home isn't just the down payment. You need to have another 2% to 5% of the purchase price set aside for the "checkout fees." In Texas, we don't have a state transfer tax (which is a huge win for you), but our property taxes and insurance are usually collected upfront, which can make that final number jump.
Lender Fees: origination fees, credit reports, and appraisals.
The Prepaids: This is usually the biggest chunk and varies depending on cost of the home. Lenders want the first year of homeowners insurance and about 3 months of property taxes paid upfront into an escrow account.
Title Fees: You’re paying a title company to make sure the seller actually owns the house and isn't hiding any "ghosts" (liens) on the property.
Note: As of March 1, 2026, the Texas Department of Insurance just dropped the base title premium rates by 6.2%. It’s not a fortune, but it’s a few hundred bucks back in your pocket.
Government Fees: Small stuff like recording the deed with Comal or Guadalupe County.
The Realistic Timeline (New Braunfels 2026)
1. Preparation
1–2 Weeks
You meet with a local lender and get a "real deal" pre-approval. No guessing.
2. The Search
1–3 Months
In New Braunfels right now, homes are sitting for an average of 87 to 120 days. You aren't in a 2021-style sprint; you're in a marathon.
3. Under Contract
30–45 Days
This is the "Contract-to-Close" period. Inspections, appraisal, and the bank doing their final math.
Traditional lenders like to see stability. If your income looks like a mountain range on a map, they get nervous. But here is the secret: They don’t just care about what you make; they care about what you keep. If you’re writing off every lunch and car wash to pay less in taxes, you’re also telling the bank you have less "income" to pay a mortgage. You have to balance being tax-smart with being mortgage-ready.
Your 3-Step Plan to Getting Approved:
Get the Truth (The 2-Year Rule): Most lenders want to see two years of self-employment in the same field. If you’ve only been at it for a year, you’ll likely need to show you were in a similar line of work for two years prior. You’ll need your tax returns (Schedule C), and possibly a Profit & Loss (P&L) statement signed by a CPA.
Get the Keys (Non-QM Loans): If your tax returns don't show enough income because of write-offs, we look at Bank Statement Loans. Instead of tax returns, the lender looks at 12–24 months of your bank deposits to calculate your "real" income. You’ll likely need a higher credit score (usually 660+) and a larger down payment (10–20%), but it gets the deal done.
Get Home (The Documentation Sprint): Start gathering your "paper trail" now. Separate your personal and business bank accounts immediately. A clean set of books is the best weapon you have to prove to a lender that you’re a safe bet.
When you’re looking at that monthly draft from your bank account, you aren't just paying for the house. You're paying for a whole team of people and protections. In the industry, we call this PITI (Principal, Interest, Taxes, and Insurance)
What is a 2-1 buydown, and how does it work?
If we lock you in at a 6.25% market rate (typical for March 2026), here is how your payments would "ramp up":
Year 1: Your rate is 2% lower (4.25%). Your payment is significantly lower.
Year 2: Your rate is 1% lower (5.25%). Still a deal, but stepping up.
Year 3-30: You hit your full note rate (6.25%).
Who pays for the 2-1 buydown—the buyer, the seller, or the lender?
1. The Seller (The Most Common Way)
In 2026, most homes are sitting on the market a bit longer. Instead of dropping the price by $20,000, a smart seller will offer to pay $10,000 toward your 2-1 buydown.
Why they do it: It costs them less than a price cut, but it makes the home much more affordable for you.
2. The Builder (The "New Home" Special)
If you’re looking at new homes in New Braunfels, builders almost always pay for the buydown. They have "preferred lenders" and use these incentives to move their inventory fast so they can start the next phase of the neighborhood.
3. The Lender (The "Wait a Minute" Way)
A lender might offer a "Lender-Paid Buydown," but remember Nothing is free. * The Catch: If the lender pays for your 2-1 buydown, they usually give you a higher base interest rate to make up for the cost. You might save money in years 1 and 2, but you’ll pay for it in years 3 through 30.
4. The Buyer (The "Pre-Paying" Way)
Yes, you can pay for your own buydown, but it’s essentially just taking $10,000 of your own cash and putting it in an escrow account to pay yourself back later.
The Guide’s Advice: Don't do this. If you have the extra cash, keep it in a high-yield savings account or use it to pay down your principal. Only do a 2-1 buydown if you can get someone else to pay for it.
MORTGAGE CALCULATOR
By checking this box, I agree by electronic signature to the Electronic Disclosure Consent Agreement; to receive recurring marketing communication from Joe Hurd, including auto-dialed calls, texts, and artificial/prerecorded voice messages (message frequency varies; data rates may apply; reply "STOP" to opt-out of texts or "HELP" for assistance); and to the Terms of Service and Privacy Policy of this website. Consent not required to make a purchase. I understand that I can call to obtain direct assistance.